• Home
  • Company
    • What we did
    • The People
    • Press
    • Around Us
  • Approach
  • Products
    • Mutual Funds
      • Pharus Asian Value Niche
      • Safe Capital Electric Mobility Value Niche
      • NEF Ethical Global Trends
      • NEF Ethical Step to Balanced 2030
      • NJ Japanese Orphan Companies
      • NJ Korea Reunification
      • NJ Indonesian Infrastructure Small Caps
  • SDG
    • SDG in words
    • SDG in videos
    • Global Compact
    • Fairr
    • SDG Events
    • SDG Academy
    • SDG Analysis
  • NicheJungle
  • Contact Us
  • Newsletter
  • English
    • Italiano
    • English
  • Home
  • Company
    • What we did
    • The People
    • Press
    • Around Us
  • Approach
  • Products
    • Mutual Funds
      • Pharus Asian Value Niche
      • Safe Capital Electric Mobility Value Niche
      • NEF Ethical Global Trends
      • NEF Ethical Step to Balanced 2030
      • NJ Japanese Orphan Companies
      • NJ Korea Reunification
      • NJ Indonesian Infrastructure Small Caps
  • SDG
    • SDG in words
    • SDG in videos
    • Global Compact
    • Fairr
    • SDG Events
    • SDG Academy
    • SDG Analysis
  • NicheJungle
  • Contact Us
  • Newsletter
  • English
    • Italiano
    • English


  • Niche AM Newsletter

    • Great opportunities don't come cheap
      October 19, 2026
    • Diagnostics faces favourable demographic tailwinds,...
      October 5, 2026
    • The Grey Discount — Chapter I
      September 2, 2026
    • No meat’s land
      July 15, 2026
    • When a bubble bursts, not everything bursts
      June 24, 2026


11
Jun
2024
Artificial Intelligence & Power
Posted On June 11, 2024  By admin  And has No Comment

Artificial intelligence is getting all the attention from investors and media right now, but if it is to become the most transformative technology of the 2020s it might in part have to depend on batteries to become so.

After all, all successful revolutions need power, and just as the clean energy revolution relies on batteries (for energy storage and transportation), so will artificial intelligence, to some degree.

AI means a lot of different things to different people, but deep down it includes some sort of intelligent machine performing the most disparate functions in the most disparate fields – including medicine, hospitality, household appliances, transportation, military applications, etc etc.

In few words, AI is supposed to give brains to a lot of these machines, but it is batteries that will allow some of these to free themselves, get up or down, and move around. According to this note, this will be the “Decade of the Batteries”.

We couldn’t agree more.

That’s why at Niche AM we have not one, but three different funds which, to a greater or lesser extent, invest in the battery ecosystem.

Both our Electric Mobility and Asian funds invest in EV & battery players which are not recognised as such by the market, and are thus deemed to have significant re-rating potential.

Our Indonesian fund invests instead in a country which is already (and will increasingly become) one of the world’s most important battery hubs. Be it for the availability in Indonesia of key battery minerals nickel and cobalt, the geopolitical “neutrality” of the country in between China and the West, and the Government’s nationalistic strategy to protect and leverage on its natural resources to develop the domestic battery industry, both downstream and mid-stream.

For details see our range of Niche AM funds & NicheJungle funds

This is a marketing communication intended exclusively for institutional investors. Refer to the Fund Prospectus & KID before making any investment decision.

For any questions email us on: info@nicheam.com

Follow us on LinkedIn: www.linkedin.com/company/niche-am


Back Read More
30
May
2024
Not only chips
Posted On May 30, 2024  By admin  And has No Comment

South Korea ain’t only about chips.

When looking at this Far East market, global investors tend to focus on the Samsungs and similar high-tech exporters. Which is clearly not a bad problem to have as an economy. Yet, South Korea is much more than that, with plenty of other sectors which are equally attractive. Or one could say, equally spicy – like noodles and ramen.

Unlike equity investors, the West’s media & entertainment industry has already noticed the potential and the quality of South Korean assets and products ex-tech, and so have consumers across the world. South Korean companies are already benefitting.

For example, Nongshim, South Korea’s leading instant noodle maker, which has announced this week that it is accelerating overseas expansion as its ramen products benefit from the growing popularity of K-pop, South Korean movies (such as Oscar-winning Parasite) and South Korean culture in general, in countries such as the US, Germany and UK. See here.

As niche investors, we scout the whole globe to try and find attractive assets which are unfairly neglected by the market and which offer huge upside potential, both in terms of cash returns and/or multiple re-rating.

South Korea’s domestic-exposed companies are among the most attractive worldwide from both a valuation and business standpoint, and our NJ South Korean fund is the only vehicle which is available to investors for buying their stock. No other funds invest in these companies, many of which are likely to rally strongly once the effects from the real estate crisis wane.

Our fund includes about 125 stock holdings; trades at around 6x earnings (yes, 6x…this is not a typo) and at circa 40% discount to TBV; and it is highly diversified in terms of sectors, with Tech representing only 4% of the portfolio while the 2 biggest sectors in terms of portfolio weight (Consumer Discretionary and Industrials) weigh just 16% each.

The possible (likely?) inclusion of South Korea in the MSCI Developed Markets index could be a catalyst for a significative revaluation of the whole South Korean market.

Some kind of change in North Korea (even minor – along the lines of past reforms in China or Vietnam) provides instead a powerful free option to which today Mr Market is assigning zero probability. Such an event should disproportionally and massively benefit our portfolio, which is mostly composed of firms exposed to the domestic economy.

Spicy broth with a meaty taste and chewy noodles may not be to everyone’s taste, but South Korea should arguably be in all global investors’ menus.

See here for details on our NJ South Korean fund.

This is a marketing communication intended exclusively for institutional investors. Refer to the Fund Prospectus & KID before making any investment decision.

For any questions email us on: info@nicheam.com

Follow us on LinkedIn: www.linkedin.com/company/niche-am


Back Read More
29
May
2024
Age matters
Posted On May 29, 2024  By admin  And has No Comment

It is said that aging doesn’t matter, unless you are cheese or, one could add, an investor.

For equity investors, population aging means labour force contraction, higher inflation, lower savings, higher interest rates, higher debt and lower economic growth, which in turn imply lower profit growth, and fewer and less attractive investment opportunities.

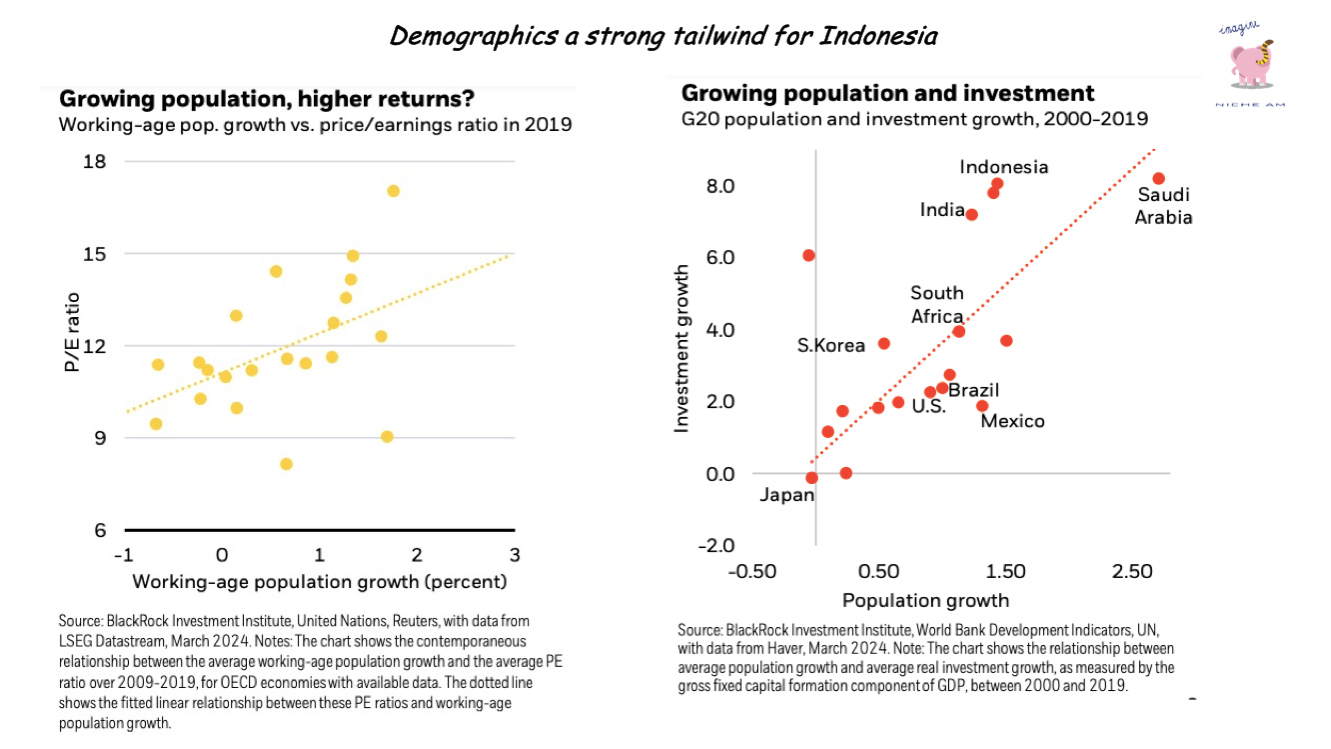
Emerging markets, thanks to growing and relatively younger populations and labour forces, should increasingly work as a hedge for aging populations in the West (and China), and stand to benefit as demographics play a bigger role in investment decisions.

This demographic dividend should be gradually reflected in valuations of EM assets, in line with what already happens to some extent within OECD countries (see this paper by Blackrock Investment Institute ).

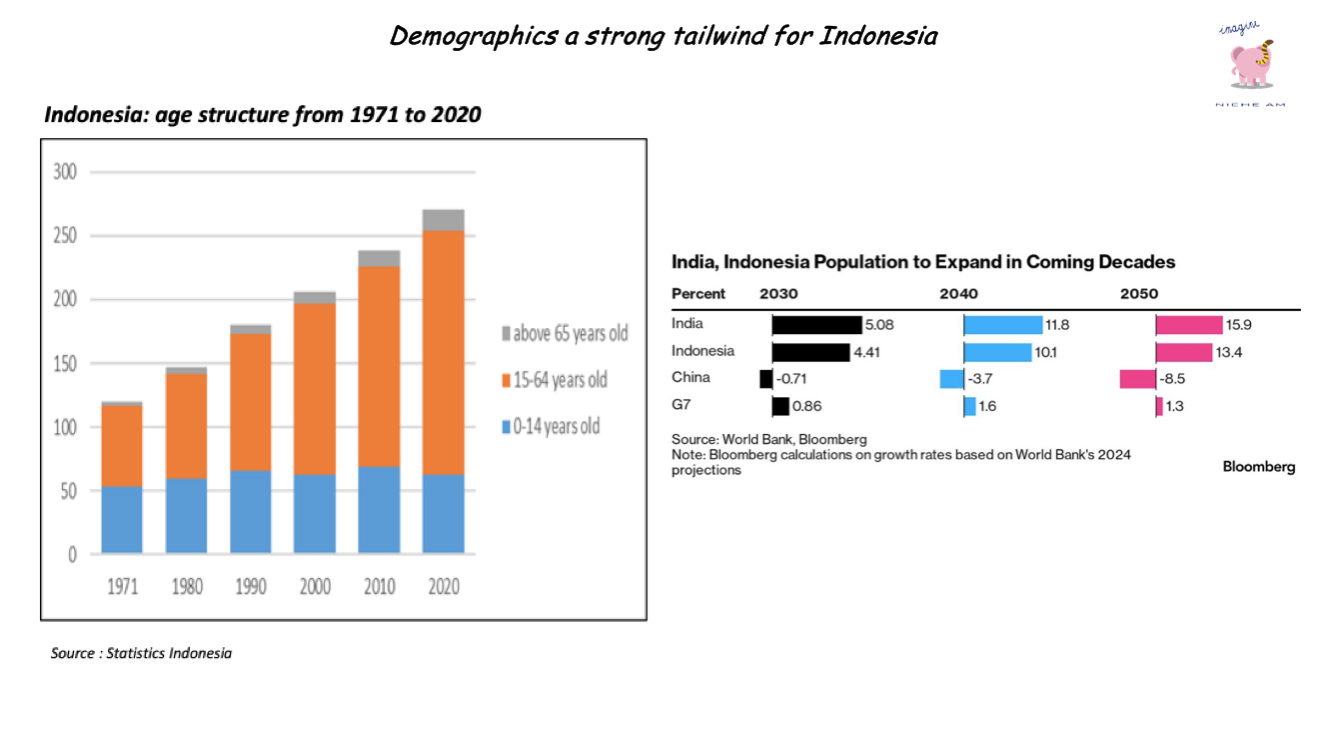
Among emerging markets, Indonesia should be one of the main beneficiaries of demographics, both in terms of profit growth, and in terms of asset re-valuation.

First, because it has one of the largest, youngest and fastest-growing population in the world. And then because of the sizeable increase in productivity which we expect to come from the enormous investments of the last and also the next 20 years, partly the result of the Government’s Golden Indonesia 2045 Vision agenda and increasing FDI.

At Niche AM we find a theme before it becomes one (and as such crowded and expensive). We believe that Indonesia ticks all the right boxes to become a mega theme for investors over the coming years, of which very favourable demographics is just one. See here for details on our NJ Indonesian fund.

This is a marketing communication intended exclusively for institutional investors. Refer to the Fund Prospectus& KID before making any investment decision.

For any questions email us on: info@nicheam.com

Follow us on LinkedIn: www.linkedin.com/company/niche-am


Back Read More
24
May
2024
The biggest invisible object on Earth
Posted On May 24, 2024  By admin  And has No Comment

When searching the web for “the biggest invisible object on Earth” one mostly gets a rather surprising result: Indonesia. Surprising because of the sheer size of the country (the Earth’s 15th largest), the population (the Earth’s 4th largest), and the economy (the Earth’s 16th largest). And yet, despite all that, it is a fact that also Indonesia’s equity market remains equally invisible for global investors.

But this may soon change.

Foreign direct investors are already noticing the country’s potential. Indonesia is already among the top 10 destinations for Chinese FDI, while US multinationals are catching up and have ranked as the 4th largest foreign direct investor in Q1 24, ahead of 5th ranking Japan. FDI in local currency has roughly doubled over the last 2 years.

Last month, Microsoft has announced an investment in Indonesia’s digital infrastructure, while only last week it was Elon Musk’s turn as he launched in Bali SpaceX’s satellite internet service for the country’s health sector.

Indonesia is admittedly still a niche, off-radar, equity market, but we are confident that stock investors will soon follow business investors and start buying the country’s deeply undervalued public equities. Mainly small caps, which are currently trading at less than 7x earnings (vs the almost 23x of their Indian peers!) and are likely to benefit from the Government’s ongoing and massive infrastructure investment programme. The current disconnect between stock and business investors is unlikely to last.

As deep value investors we are generally happy to buy an asset as soon as we see an attractive yield, without the need to wait for a catalyst – which often remains invisible until it’s too late. And in fact, we see that attractive return for Indonesian stocks already today. Having said that, we do anticipate at least 3 possible catalysts:

  1. Satya Nadella and Elon Musk’s investments are just two high-profile examples of what could follow in terms of FDI news-flow, something which could help put Indonesia on stock investors’ radars, especially as the country benefits from industrial re-shoring out of China and from the world’s appetite for Indonesian natural resources.

  2. Declining US inflation and interest rates (if they were to remain on a downward path) should also benefit Indonesia, along with its EM peers.:

  3. An increasingly expensive equity market in India and the fear of a possible correction or crash could gradually or suddenly convince investors to switch into cheaper Indonesia.:

Indonesia doesn’t deserve to remain invisible, and we are confident it won’t stay so for much longer. See here for details about our unique Indonesian niche fund.

This is a marketing communication intended exclusively for institutional investors. Refer to the Fund Prospectus & KID before making any investment decision.

For any questions email us on: info@nicheam.com

Follow us on LinkedIn: www.linkedin.com/company/niche-am


Back Read More
10
May
2024
Empowering Indonesia
Posted On May 10, 2024  By admin  And has No Comment

Niche AM’s mission is to discover an investment theme before it becomes one (and therefore before it becomes expensive and overcrowded).

Niche AM believes Indonesia could become one of these “super themes” in the years to come, perhaps the emerging market darling of the next 5 years, replicating the performances of China in the 2000s and India in recent years.

The country certainly has all the potential to become such a theme, and it also has a number of possible catalysts on the horizon.

Infrastructure investment is one of these key catalysts. Not only from Government, but also from foreign investors, as Indonesia capitalises on growing political and economic stability, and as it benefits from its key geopolitical position: standing right in the middle of the geopolitical fault line between China and the West could help Indonesia attract FDI at increasing rates from both sides.

This is not wishful thinking.

Only last week Microsoft has announced an investment in Indonesia’s digital (cloud and AI) infrastructure, which -albeit not sizeable relative to the country’s GDP- is yet another sign of Indonesia’s benign FDI outlook (see here).

Microsoft’s digital infrastructure investment follows last November’s signature between Indonesia and the US Government of a new partnership to explore supply chain opportunities in the strategic semiconductor sector (see this), and builds on the company’s “Empower Indonesia” initiative, which includes plans to roll out Microsoft’s first data-center region in the country (see here).

With the highest number of micro and small enterprises per capita in the world (and a geographic and logistical dispersion which is probably also unique in the world) digitalisation should massively boost productivity across the archipelago.

According to research by Kearney, AI alone could contribute nearly US$1 trillion to Southeast Asia’s GDP by 2030, of which Indonesia is poised to capture more than US$365 billion.

See here for details on our investment case on Indonesia and our NJ Indonesian fund.

This is a marketing communication intended exclusively for institutional investors. Refer to the Fund Prospectus & KIDs before making any investment decision.

For any questions email us on: info@nicheam.com

Follow us on LinkedIn: www.linkedin.com/company/niche-am


Back Read More
07
May
2024
Does ESG outperform or underperform?
Posted On May 7, 2024  By admin  And has No Comment

European investors’ net allocations to ESG ETFs have almost halved to ~€7bn in Q1 24 vs Q4 23, with sales down to just 16% of total ETF inflows during the quarter, compared with 29% in Q4 23 and 65% at the height of investor ESG euphoria in 2022 (see here).

According to Morningstar, ESG investing appears to be going through “a period of existential crisis” as investors have allegedly become concerned about the underperformance of ESG investments.

Yet, performance, as beauty, is often in the eye of the beholder. All of our funds are ESG compliant – actually, they are more than that, they are also Article 8, 8+ or even 9 SFDR. But not because we claim that ESG outperforms. Whether or not it does, it mostly depends on the data used to assess performance. As Chicago’s Coase once famously claimed, “if you torture the data long enough, they will confess to anything”.

For us, all what ESG & SDG investing does is providing portfolios with a superior risk/benefit profile (which is no small feat). In our view, ESG helps reducing regulatory, political and legal risks (in the sense of helping avoid courts and potentially huge legal bills), while SDG ensures investments in high-growth sectors (helping avoid old economy’s value traps).

Our ESG approach is also so to speak “macro”, meaning that we don’t invest in autocracies (which helps avoid all sorts of risks), nor we invest in those countries which are in FATF’s grey list for money-laundering. With no ifs and buts, we also exclude from all our funds sectors such as tobacco and weapons – no matter how these sectors are “improving” from being deadly to being less deadly.

This brings us to a final, but not less important feature of our ESG approach: we don’t just “screen off” potential portfolio holdings based on external ESG-score providers.

For 3 main reasons: for starters, these ESG-scores vary dramatically from one to another provider; they are often not available for the micro, small and mid-cap companies in which our funds frequently invest; and finally, they are often quite puzzling. For example, S&P Global’s latest ESG score for Philip Morris, whose cigarettes continue to cause ill health and death around the world, is 85 out of 100, while the score for Tesla, with its transformational contribution to the shift away from fossil fuels, is just 40! (as well explained here).

So how do we do it? We use an integrated approach, combining our own, proprietary sustainability analysis (both quantitative and qualitative) with intensive corporate engagement, mainly aimed at accompanying small and micro-caps (which have more limited resources) on their paths towards sustainability.

Further details of our approach here and here.

This is a marketing communication intended exclusively for institutional investors. Refer to Fund Prospectuses & KIDs before making any investment decision.

For any questions email us on: info@nicheam.com

Follow us on LinkedIn: www.linkedin.com/company/niche-am


Back Read More
22
Mar
2024
No SFDR Article 9 in Italy’s insurance-based investment products
Posted On March 22, 2024  By admin  And has No Comment

Italy’s Insurance Regulator IVASS has recently conducted a study into the country’s unit-linked policies and other insurance-based investment products which was aimed at intercepting possible cases of greenwashing in the industry.

The study has assessed sustainability claims of over 100 domestic policies, related to over 1 million contracts and approximately €50bn of insurance premia. You can read the full report here.

While the IVASS analysis did not reveal any obvious cases of greenwashing, it also highlighted the substantial absence in the domestic insurance market of so-called “dark green” products, i.e.policies that include sustainable investments as an objective of the investment policy (Article 9 products as per the EU’s SFDR).

About 92% of products are instead classified as “light green”, that is Art. 8 products that promote, among others, environmental or social characteristics in investment policies, while the remaining 8% are not even “light green” but just Article 6 products which only include sustainability risks in investment choices.

Interestingly, the study has perceived a degree of caution by asset managers when classifying the products as as as “light green“, “dark green” or Article 6, reflecting the possibility of “bleach-washing” (that is, when asset managers prefer not to define a financial product as more or less sustainable in order to reduce disclosure obligations and avoid legal risks).

Niche Asset Management manages two Article 9 SFDR funds, which as well as being 100% sustainable are also thematic, global and managed with a deep value investment approach: the Electric Mobility Value Niche, a high-growth theme fund, trading at deep-value multiples and managed by the team that in 2015 launched the world’s 1st electric mobility fund ever; and NEF Global Ethical Trends, a global ex China fund with about 275 stocks spread across 27 thematic portfolios functional to the achievement of the United Nations’ Sustainable Development Goals.

Our deep value approach, which guarantees extremely low turnover, enables continuous engagement between Niche AM and the management of companies in the portfolio, thus allowing careful monitoring of corporate sustainability policies.

We do not do purely formal screening-offs or tick-the-box analyses. No green-washing, and certainly no bleach-washing.

For details on both funds see here.

This is a marketing communication for institutional investors. Please refer to Fund Prospectuses & KIDs before making any investment decision.

For any questions email us on: info@nicheam.com

Follow us on LinkedIn: www.linkedin.com/company/niche-am


Back Read More
08
Mar
2024
Are stocks in a bubble which may be about to pop?
Posted On March 8, 2024  By admin  And has No Comment

Are stocks in a bubble which may be about to pop?

Who knows.

There certainly seems to be a degree of irrational exuberance in some pockets of the equity market, but as Keynes has famously observed markets can stay irrational for longer than one can stay solvent. Most importantly, the variables we need to know to solve the bubble equation (inflation, interest rates, liquidity, productivity, geopolitics, etc) are too many and mostly imponderable.

However, while we can’t predict we can certainly be prepared.

And the way to be prepared is and has always been to hold a properly diversified portfolio – in terms of investment style, industry, market cap size, number of holdings and geographical and currency exposure.

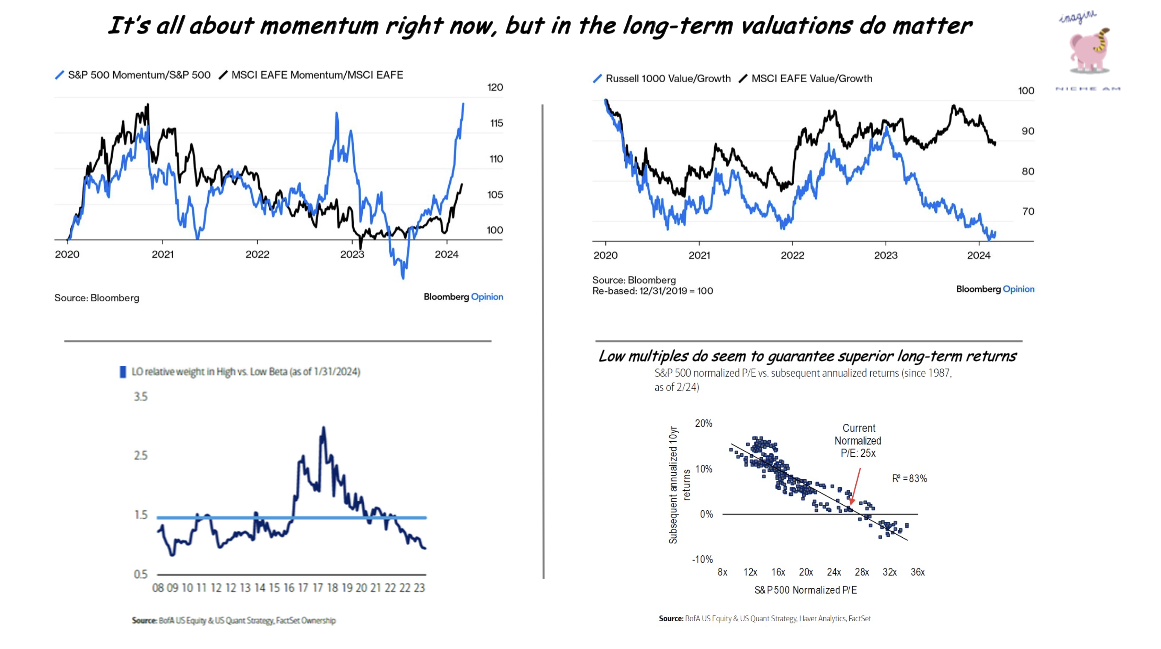
Investors are currently overexposed to seemingly expensive and overcrowded momentum strategies, paying arguably excessive premia for a very small fraction of mainly big-cap stocks within über-concentrated portfolios.

Niche AM funds provide investors with a much-needed, prudent counterbalance, through highly liquid and diversified portfolios of value stocks, many of which are found among neglected sectors and overlooked geographies.

Value stocks have rarely been as cheap and as attractive in terms of financial strength, earnings prospects and sector breadth as today. The style should benefit going forward from the boost to global economic growth which could come from two likely and massive secular trends, i.e. energy transition and deglobalisation.

True, valuation has seldom been a strong predictor of short-term stock performance (as the near term is often dominated by the “noise” of news-flow, fads and emotions), but it seems to be a strong predictor for the longer-term, explaining on some estimates about 80% of 10-year stock returns.

While history doesn’t repeat itself, it does often rhyme and perhaps it is worth remembering that in the 10 years after the burst of the 2000 tech-bubble, value strategies have significantly outperformed.

To sum up, and paraphrasing Buffett, you can’t predict a bubble or a bubble bursting, but you can make sure you are not caught swimming naked when the tide goes out.

This is a marketing communication for institutional investors. Please refer to Fund Prospectuses & KIDs before making any investment decision.

For any questions email us on: info@nicheam.com

Follow us on LinkedIn: www.linkedin.com/company/niche-am


Back Read More
21
Feb
2024
Has passive investment broken value investing?
Posted On February 21, 2024  By admin  And has No Comment

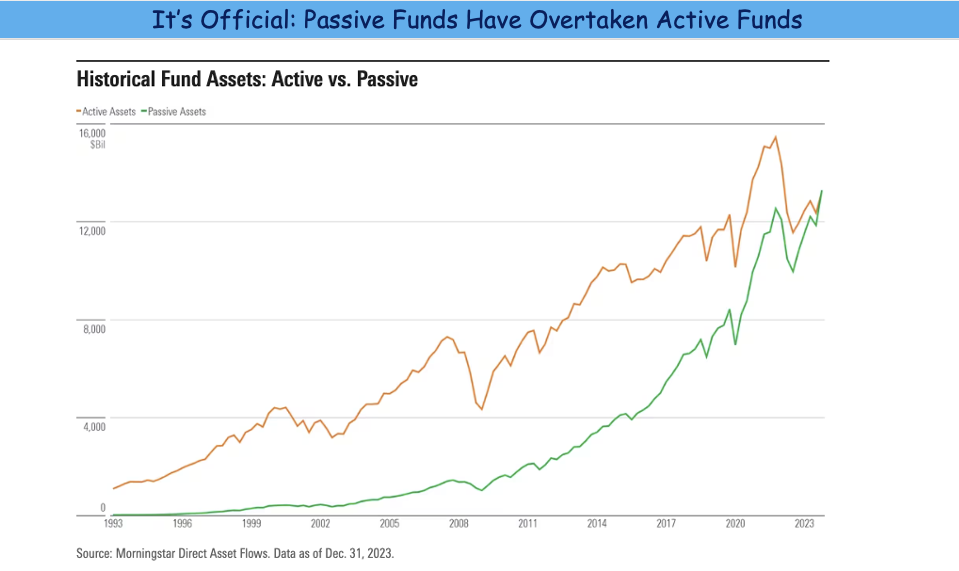
Has passive investment broken value investing, as argued by Greenlight Capital’s Einhorn? See here.

The logic is clear. By throwing in a wall of money onto stocks, or withdrawing that wall, no matter the valuation or fundamental strength of the underlying company, index investing undermines the signalling function of market prices for the allocation of capital and along with that the efficacy of value investing.

Passive investors – Einhorn’s argument goes on – have no opinion about value, which means that “when money is moved from active to passive, value managers get redeemed, value stocks
go down, it causes more redemptions of value managers, it causes those stocks to go down more and so on”. The conclusion sounds somewhat apocalyptic: “the value industry has gotten completely annihilated”.

There is certainly some truth in this argument, but paraphrasing Mark Twain, reports of our death are greatly exaggerated.

Passive investing in the US, the world’s biggest market, is (for now) only ~50% of institutional equity funds, which means that the remaining US$14.3 trillion of active investing is reasonably
more than enough for the price discovery mechanism to continue functioning. In fact, just a small share of fundamental, active investing would probably do the job.

In general, there is ample evidence that passive and active value strategies complement each other, with passive being often the core of a portfolio and active value a portion allocated for
potential outperformance, thematic exposure and risk mitigation. Today, value investing provides a much-needed counterbalance to passive investing and to investor euphoria about technology stocks.

This is a marketing communication for institutional investors. Please refer to Fund Prospectuses & KIDs before making any investment decision.

For any questions email us on: info@nicheam.com

Follow us on LinkedIn: www.linkedin.com/company/niche-am

 
Back

Read More
09
Feb
2024
Does thematic investing create value for investors?
Posted On February 9, 2024  By admin  And has No Comment

Does thematic investing create value for investors?

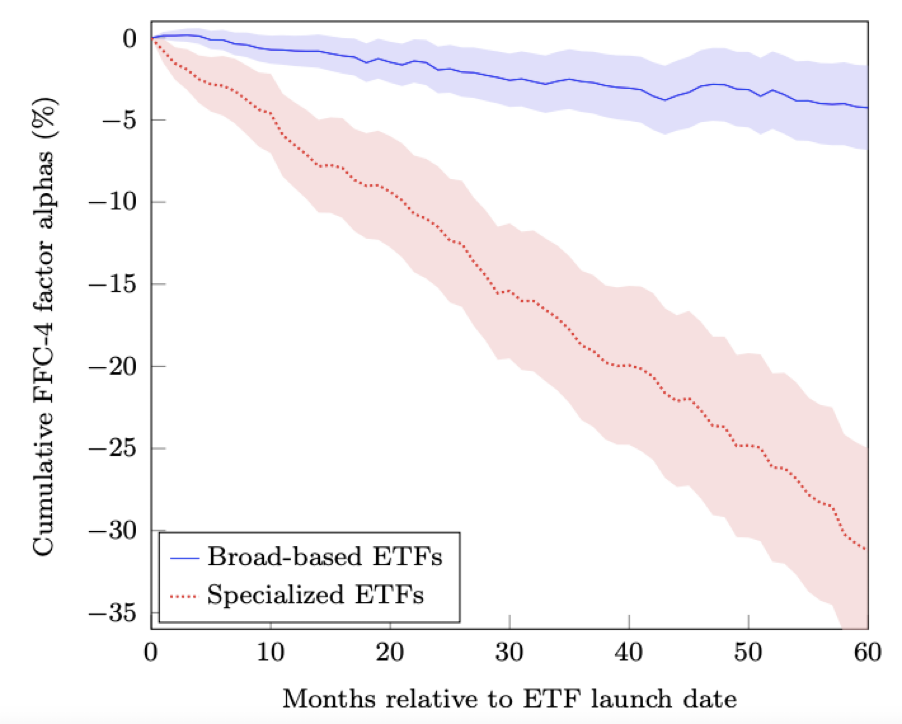
Not quite, according to this NBER paper which shows that at least in the ETF space, thematic investments underperform broader funds by about a third over the five years after launch, delivering negative alpha of about -4% a year.

The argument is not new: thematic ETFs are generally launched just after the very peak of excitement around an investment theme, holding portfolios of “hot” assets already overvalued at
launch and with über-high expectations. As industry and media hype vanish or financials disappoint, thematic investment underperforms or delivers negative risk-adjusted returns.

We couldn’t agree more.

That’s why at Niche AM we don’t really invest in themes but rather in niches, i.e. assets or themes which are all but neglected by the market and are thus deeply undervalued and entirely off-radar for investors and media.

Niche AM’s mission is somehow to find a theme before it becomes so. The niche may take time to attract investors and deliver potentially strong returns, but the enormous valuation opportunity makes it worth the wait.

This is a marketing communication for institutional investors. Please refer to Fund Prospectuses & KIDs before making any investment decision.

For any questions email us on: info@nicheam.com

Follow us on LinkedIn: www.linkedin.com/company/niche-am


Back Read More

123456789
Page 3 of 9

unglobalcompact fairr

Niche Asset Management ltd is authorised and regulated by the Financial Conduct Authority, FRN 783048
Legal | Cookie Policy