Japanese Secrets
In Japan, shinise (literally “old shops”) are long-established businesses that have been in operation for at least a hundred years – some even more than a thousand years.
These businesses have endured nuclear wars, earthquakes, tsunamis and depressions, and yet, as explained here by Morgan Housel, they keep going on, generation after generation.
Japan is in fact the country with the biggest number of such old businesses, with their products and services clearly enjoying immense prestige (one of these being for example the household brand-name Nintendo).
What is their secret? The reasons for their success are probably many, but there is one that could surprise those used to Western-style capitalism: these Japanese companies hold tons of cash, and no (or very low) debt.
Low leverage certainly helps survival. As illustrated by Housel, with no debt, the number of events a company can withstand might fall within a range that looks like this:
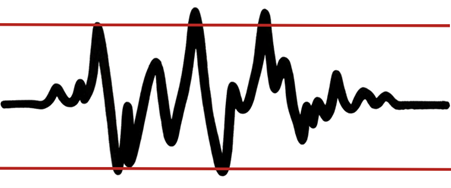
A few catastrophic events might hurt, but you are likely to survive.
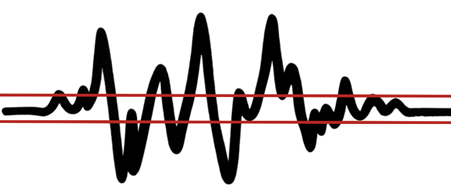
With more and more debt, says Housel, the range of events you can survive shrinks until you are toast:
What’s all this got to do with us?
At Niche AM we run a Japanese fund that invests in what we call “orphan companies”, i.e.: companies not covered by the sell-side and thus significantly undervalued. But lack of broker coverage is just one of the features of our fund.
As deep value investors, we can’t but appreciate the business approach of shinise. And consistent with that view, in our portfolio we only hold companies which -like shinise – are net cash positive. In fact, the companies in our Japanese Orphan Companies fund have roughly, on average, 10% more cash than their market cap:

For further details on our Japanese fund see here.

This is a marketing communication intended exclusively for institutional investors.
Refer to Fund Prospectuses & KIDs before making any investment decision.
For any questions email us on: info@nicheam.com
Follow us on LinkedIn: www.linkedin.com/company/niche-am
Back Read More
 This even though the bank was apparently a solid global financial institution. However, family offices, funds and rich people who read daily negative press about the institution where they store their cash, may have been asking themselves questions. A frontal press attack, devoid of substance, occurred in October, right during the company’s black period. This led to an initial bank run that culminated in a capital increase that, on paper, was not needed. Arab investors increased their positions, and the bank decided to accelerate its transition to a low-risk reality.
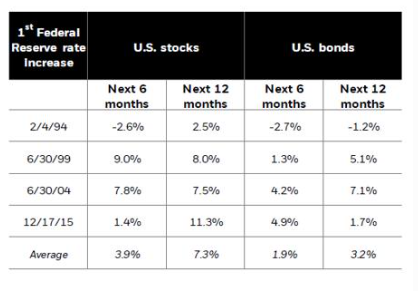 Why? 1) The housing market, residential and commercial, is not in a bubble. The imbalance between supply and demand is substantial as a result of years of under-investment linked to the scarcity of bank financing in this sector. The end of the pandemic will lead to a recovery in demand for office space and confirm the home as the place to work. Inflation is also another support for this asset class. 2) Consumption accounts for about ¾ of GDP in the US. Today’s consumption dynamics are negative, as is natural after the market crash and recession fears. However, the labour market is extremely strong and this is the backbone of consumption. The relocation of many manufacturing industries will maintain full employment and, along with this, a positive wage dynamic in real terms. Bonds finally provide attractive yields for savers. The stock market has corrected from the tech bubble and the traditional side is extremely attractive and will gradually appreciate again in the not too distant future. This tells us that consumption will be robust in 2023, recovering from 2022. 3) Corporate profits will nominally benefit from inflation, absorbing any inevitable pressures during a rate adjustment phase. In addition, many industries, such as finance, armaments, fossil fuels, and everything related to infrastructure and energy transition, will grow in the next 12 to 24 months. 4) There has been a shift in the US from an attitude of complacency towards inflation to one of strong fear. So much so that by now there is no longer talk of recession but of stagflation, something not seen for 40 years, in completely different environments (Volcker at the FED and Ronald Reagan in the White House). Today, however, inflation is coming down and gradually in the coming weeks and months we will begin to see it in the numbers. The fall in commodities prices these days and the gradual unwinding of the supply chain will contribute to this. The overstocking created precisely to address these problems in the supply chain will lead to substantial discount campaigns. The rate hike cycle will be powerful but entirely manageable, and we believe that the Fed’s current expectations of 3.8% for 2023 will not be revised upwards but may even be tweaked slightly downwards in the not-too-distant future (3.4% at the end of 2022).
 Banks range from-35%(JPM, Bank of America, Wells Fargo) to over -40% (Citigroup). Insurance companies from -20% to -40% (Metlife -17%, Prudential -25%, Lincoln -39%). Transportation companies, those most anticipating a recession, from -30% to -40% (Fedex -29%, UPS -27%, DPW -43%), retailers from -30% to -50% (Home Depot -35%, Kohls -38%, Macy’s -47%, Target -48%), cement and building materials from -30% to -60% (Martin Marietta -31%, Vulcan Materials -31%, CRH -34%, Tutor Perini -58%), finally, automotive by more than 50% (GM -53%, Ford -56%). All the sectors mentioned are not comparable with the same sectors in 2007 or even 2020. Today they are much stronger and have better medium-term prospects. In addition, the consumer is less indebted and scared.